
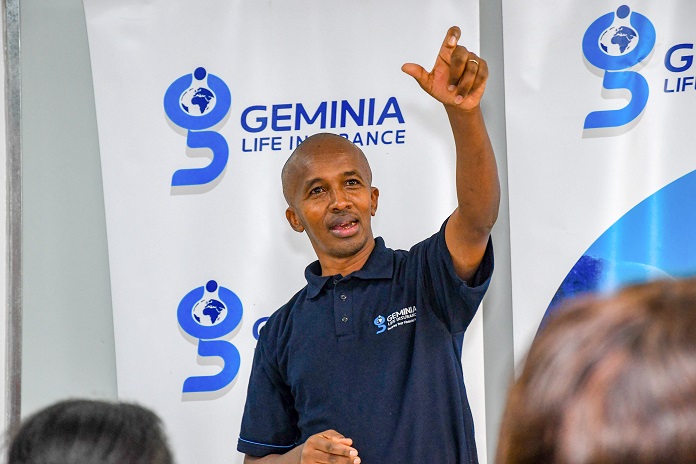
Having and creating a retirement plan is vital. A pension plan is important as it helps individuals maintain and sustain their standard of living after retirement. However, it is worth noting that pension in Kenya is not that common and many people, especially those in the informal sector, are yet to have retirement plans. To learn more about how people can save up for retirement, Destin Africa interviews Mr. Daniel Wang’endo, Business Development Manager, Retail Lines, Geminia Life Insurance Co Ltd. Mr. Wang’endo talks about Geminia Personal Pension Plan (PPP), a product designed to offer individuals a platform to secure their future by making regular contributions during their active working life. The company invests the pension fund to generate an income that is added to one’s contribution to make it grow in readiness for when they retire
How do you demonstrate the value proposition of Geminia Life as a reputable and trusted insurance company that offers affordable, flexible, and secure personal pension plans?
Geminia Life has been in the Life Insurance sector for over thirty years now. To be present and thrive for three decades shows that the company is doing things right. It has been thirty years of understanding the market and listening and responding to the customer, and especially keeping the promise. At Geminia Life Insurance we promise to be there for the customers when they need us the most, and that we do everything in our powers. About the safety of the customer’s pension funds, we have a very robust internal risk management culture to ensure that the client’s money is invested in the way stipulated by the Law. Aside from that, as you know, we are regulated by the Retirement Benefits Authority (RBA), and this provides an extra layer of protection for retirement savings. Our clients’ retirement fund is as safe and growing!
What are the main features of Geminia personal pension plans?
The Geminia Personal Pension Plan provides a platform to save up for retirement from a minimum contribution of Kes 2,000 to any amount. It is also one of the highest returning pension schemes in Kenya today, with an average of 9.29% over the last six years. Anyone can start saving because the payment plan is flexible; you can save up monthly, quarterly, half-yearly, annually or whenever funds are available. If one misses a contribution they can start from where they left, without any penalties. We also have several payment methods such as MPESA, Salary deduction and bank transfers. Notto mention the tax benefits that one enjoys by participating in a pension scheme.
What are the main differences between a provident plan and a pension plan, and how would you help a customer choose the best option for their retirement goals?
The difference really is in the treatment of the benefits at retirement, all else is the same. When a member who is in pension plan retires, one third of their total benefits is paid to them in cash, as lump sum and the rest is spread out as a regular payment throughout their lives. In a provident fund, the full benefits are paid out to the member at retirement as a lump sum. The choice on which one to take, is based mostly on the customer’s unique circumstances and sometimes behaviour. If as a customer you know that your spending habits may not leave you much to last the no-income season, then a pension plan is safer. We’ve heard of cases where a retiree is paid in full and gets into an entertainment spot for the night only to end up broke the next morning. Some clients, on the other hand, are happier controlling their investments or already have income plans that can protect the benefits from inflation, and so a provident is perfect. So, clients are guided by our pension experts based on a complete understanding of their risk and investment persona.
Can a customer withdraw or transfer their personal pension fund before retirement, and what are the implications of doing so?
Yes. The law permits both transfers and withdrawals. There are no costs for transferring one’s pension. Pension funds transferred from an occupational scheme are accessible after turning fifty years. However, if they withdraw their contributions before the retirement age, the benefits are subjected to applicable taxes, depending on their age. One is therefore able to withdraw 100% of their own contribution from a Personal Pension Plan.
What are latest trends and developments in the personal pension industry?
Allow me to flip the question to, “what is the biggest concern among Pension Providers like us, regarding retirement planning in the country?” Why this is critical is because, the truth is, Kenyans are not saving enough. People are retiring poor and if current savings is anything to go by, the trend is not changing soon. You see, retirement planning is a very personal journey. Some people believe that livestock, land and other traditional tools are sufficient. Yet, how does this behave against the unpredictability of the demand? We like to speak of the Income Replacement Ratio as a determinant for what you need to save. Income replacement ratio is simply the proportion of your current income that you need to receive in retirement to maintain the lifestyle you are currently used to or something close. The ratio varies but it is safe to target anything upwards of 60%. Our concern as a company, and hopefully as a nation is on the effectiveness of appropriate tools for comprehensive social protection for the people of this country.